The ECB has already lifted its key rate twice this summer but investors see another three or four moves in the next year as both oil and gas prices are now at its “severe” scenario and inflation could peak at around 4%, twice the bank’s target
International News via Reuters:
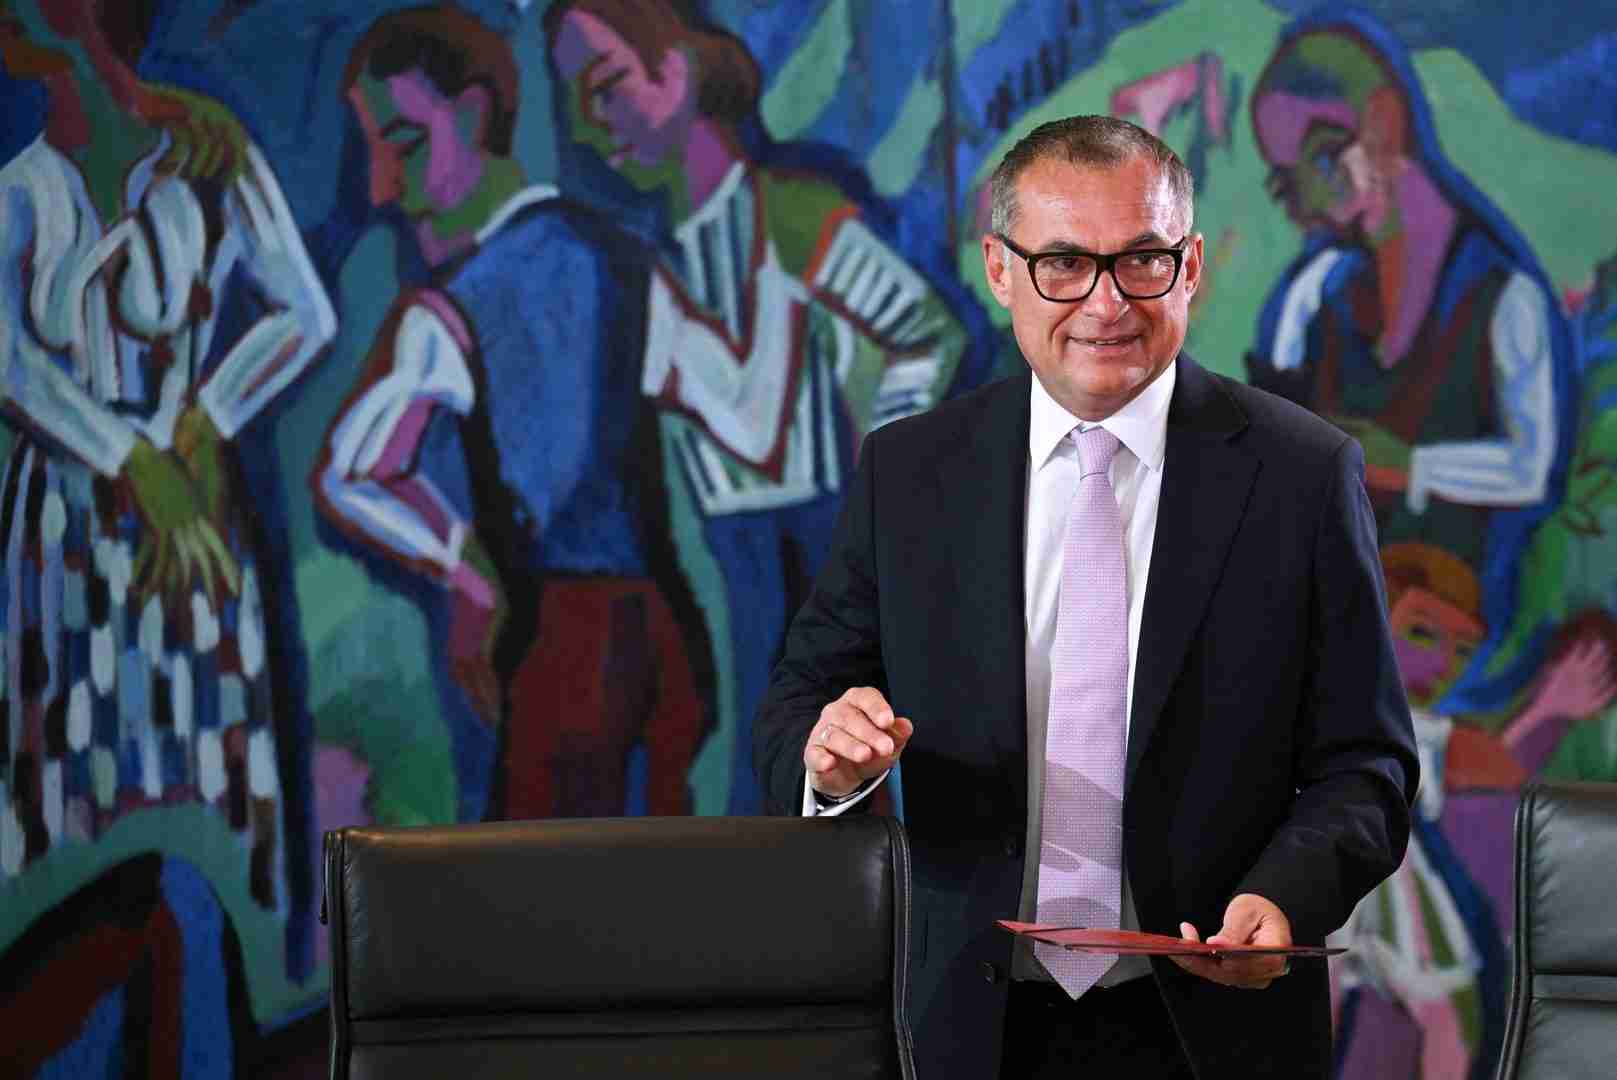
Oil prices are an increasingly important indicator for ECB policymakers in setting interest rates but other factors also play a crucial role, Bundesbank President Joachim Nagel said on Tuesday after markets raised rate-hike bets on expensive energy.
The ECB has already lifted its key rate twice this summer but investors see another three or four moves in the next year as both oil and gas prices are now at its “severe” scenario and inflation could peak at around 4%, twice the bank’s target.
ECB President Christine Lagarde and Vice President Boris Vujcic have both pushed back on those bets, arguing that rates do not move in lockstep with oil prices. Their remarks suggested the bank may wait until December to pull the trigger next.
“It’s definitely not the only indicator but it’s become a more relevant indicator over the last four years, this is for sure,” Nagel told an event hosted by London’s Society of Professional Economists.
“It is obvious that we in governing council have to look at it and we have to take it into account when we take our decisions,” he said about oil prices.
Still, he kept open the door to more rate hikes. He said rates, now at 2.5%, are in a territory that neither restrict economic growth nor stimulate it.
“I cannot exclude that if we are confronted with higher energy prices like this, that we have to go into the mild restrictive territory of monetary policy,” he said.
But he played down some worries about second-round inflation effects, arguing that the labour market was far softer than in 2022, when an energy-price-led inflation fuelled increasing wage demands, leading to a wage-price spiral.
He also said there were no significant second-round effects in the data.
For now, the ECB needed to maintain its approach of making decisions meeting by meeting, Nagel said.
This means that policy needs to be somewhere between “constructive ambiguity,” or intentional policy vagueness, and setting “forward guidance” or making explicit commitments about future policy moves, Nagel said.
Reporting by David Milliken; writing by Balazs Koranyi; Editing by David Gregorio