Wednesday, October 28, 2026
Home Blog Page 892

Inside the airline seat industry crisis delaying jet deliveries

Beneath a luxury business class armrest lies a key bottleneck slowing global aircraft deliveries
International News via Reuters:

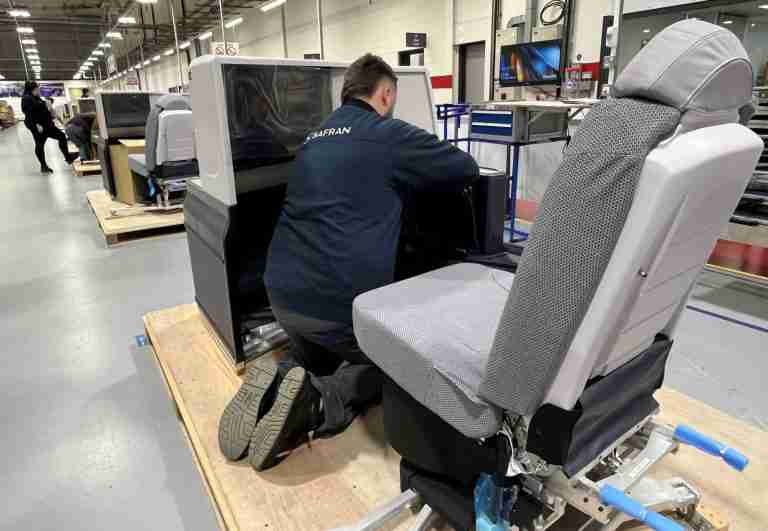
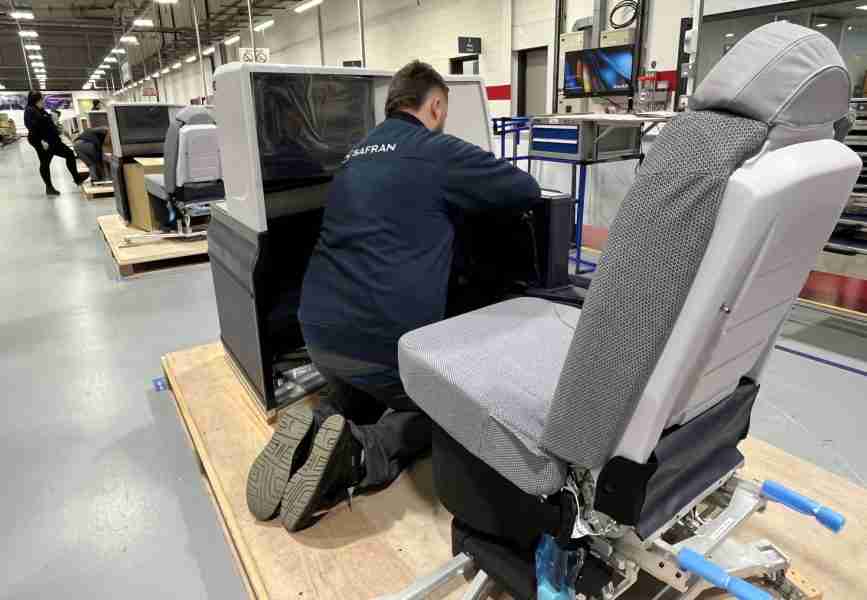
Tucked beneath the armrest of a luxury business class seat in a factory in Wales lies a clue to a global aviation bottleneck that has left many airlines waiting impatiently for new jets.

Before the armrest can support the pampered elbow of a premium passenger, a complex manufacturing jigsaw with as many as 3,000 parts from 50 suppliers in 15 countries needs to be meticulously assembled to produce the luxury seat.

As air travel grows, this niche but critical part of the aerospace industry is at the centre of efforts to clear a logjam that has contributed to billions of dollars of aircraft delays for industry giants Airbus and Boeing, and higher fares for passengers.

“If you look at this, all you would see is a top-level arm cap and think that’s very nice,” Dafydd Davies, industrial vice president at Safran Seats GB, said during a visit to the company’s factory in Cwmbran, South Wales. “If you look below, there is a lot more to the mechanical assembly.”

To understand the often overlooked issue of how something as outwardly simple as a seat can slow the entire jet supply chain, Reuters spoke to over a dozen people involved in seat making and purchasing, airline chief executives and designers.

Coupled with bottlenecks in certification, growing airline demand for bespoke features has made it hard for a fragmented seat industry – only now getting back on its feet after the COVID pandemic – to achieve economies of scale and boost output.

“There has been a perfect storm of what would otherwise not be industry-stopping problems,” said aircraft interiors expert John Walton, founder of specialist publication The Up Front. “It’s still very much a cottage industry.”

Airbus warned airlines in May that delivery delays could persist for another three years as it works through a backlog of supply problems, which it blames chiefly on engines and seats.

With air travel rebounding from the pandemic, airlines will need more than 8 million seats in the next decade, according to a study by Tronos Aviation Consultancy and AeroDynamic Advisory.

It’s a business worth $52 billion over 10 years.

The cabin of a long-haul jet contains some of the world’s prime revenue-generating real estate, which is why airlines are prepared to pay $80,000-$100,000 for a business-class seat and an astonishing $1 million for a first-class suite, insiders say.

“There are only a few truly differentiated things you can do onboard as an airline: the crew, the seat, the catering. Not so much the aircraft. So that’s where we’re going in the premium classes,” said Lufthansa Group Chief Executive Carsten Spohr.

ALADDIN’S CAVE

At the airline industry’s annual Oscars every April in the German city of Hamburg, honours are handed out for inventions such as smart lavatories, smart seats and even smart bins.

Entrance to the Aircraft Interiors exhibition is strictly by invitation and rows of showrooms are protected by security worthy of a jewellery store. Inside, each is an Aladdin’s cave of fast connectivity, eco-friendly materials and recently launched comforts such as headrests with built in audio.

The most advanced innovations are even further out of sight.

“It’s a secretive world. Sometimes they have the little back rooms where they’ve got a seat or product they haven’t publicly talked about,” Steven Greenway, CEO of Saudi carrier Flyadeal, said as he shopped for premium seats for Airbus A330neo jets.

But behind the curtain is an industry struggling to graduate from a craftsman-like approach and small production runs to industrial scale – despite waves of consolidation which have whittled the sector down to two main rivals in premium seats: France’s Safran and RTX unit Collins Aerospace.

Then comes Germany’s Recaro Aircraft Seating, which dominates economy seating but has struggled to break into premium, and rivals including China-owned Thompson Aero Seating and ventures backed by Airbus and Boeing: Stelia and Elevate.

“They compete on innovation, yes, but when they produce, it’s not as reliable as the car industry,” said Lufthansa’s Spohr, whose airline has waited months for Boeing 787s grounded by missing seats, commenting on the overall seat industry.

Longer ranges for smaller planes have also triggered a scramble to adapt premium seat designs to tighter spaces. Even the tapered shape of a fuselage and differences between left and right mean few luxury seats are exactly the same.

Added to that are tough certification requirements designed to protect head impact, and a dearth of certification engineers.

Seats typically last about seven years whereas planes themselves fly for 20-25 years, so even when jets are finally delivered, the need for new seats soon comes around again.

“It’s been a problem for 20 years. It’s not just a recent issue. But I think it’s got worse,” Willie Walsh, director general of the International Air Transport Association and former head of British Airways, told Reuters.

INDUSTRY REBOOT

Failing to put the industry on a more solid footing could crimp the growth plans of airlines or force carriers to fly older planes for longer, and focus more on refurbishments.

Now, some seat makers are trying to simplify production as they rebuild fragile global supply chains.

Safran is one. Its seats unit finally broke even in the fourth quarter of 2024 after being battered, like many of its rivals, by the slump in demand during the global pandemic.

“We’ve almost had to restart this industry. We’ve had to ramp back up again. We lost some longevity in talent because they decided to do something else,” said Safran Seats Chief Executive Victoria Foy.

“The fact that we got 2.5 times more out the door in 2024 than the year before demonstrates we can ramp up,” she said in an interview at the company’s Cwmbran factory.

On the factory floor, chips, screens and motors are pieced together in individual bays rather than on a moving production line since few luxury seats are the same. A walled-off workshop for first-class seats guarantees even more individual attention.

“We are managing a similar level of requirements to that of a landing gear or an engine,” Foy said.

Under pressure to avoid those spiralling out of control, Safran and others are now rethinking the way they build seats to marry the customised flourishes required by many airlines with the cookie-cutter approach needed for efficient assembly.

Instead of developing each seat from scratch, manufacturers are looking to re-use underlying designs, much in the way auto makers often use one chassis for different models and brands.

Using a limited set of underlying designs allows seat companies to do the basic engineering and certification earlier on, avoiding the risk of delays later in the process.

But it’s not just about improving the factory floor.

Air travel is changing, said Stan Kottke, president of interiors at Collins Aerospace.

In the Middle East, more families fly in business class. In the United States, retirees want to travel in an ergonomic seat. Millennials are investing in high-end travel experiences.

They all want something different from the typical business nomad and airlines may even have to cater to different users at different times of day, Kottke told Reuters in an interview.

“You can build a platform that is deliberately designed for differentiation in a bunch of different directions,” he said.

STRAINED RELATIONSHIPS

The disciplined approach is reshaping negotiations with airlines, where the CEO is often personally involved in the finer points of cabin design.

In a change of tone, suppliers are increasingly turning away business rather than chasing every deal, four people with direct knowledge of such talks said. In tenders, the reply “no bid” has become common, as seat suppliers avoid piling up financial risk.

The industrial blockage has strained the delicate three-way relationship between planemakers, suppliers and carriers.

Airlines often buy seats directly from suppliers such as Safran, Collins or Recaro but get Airbus or Boeing to fit them.

Airbus is now exploring ways of charging seat firms penalties for delays that hold up deliveries of jets from its factories, two people familiar with the discussions said.

None of the companies commented on contractual matters.

Planemakers must also walk a tightrope between marketing the flexibility of their cabins while nudging airlines towards accepting greater standardisation to alleviate supply problems.

Airbus has said it is acting to reduce risks to its own ramp-up plans from the “divergent complexity” of bespoke interiors, while Boeing has said the resulting bottlenecks in certification will be a challenge for the rest of this year.

The two giants have a powerful ally in the leasing industry.

“My advice to all airline CEOs would be … stop inventing more seats. I know every airline CEO wants to design their own business class seat – don’t do it,” said Aengus Kelly, chief executive of the world’s largest aircraft lessor AerCap.

“Take one that is certified, that’s a very good product, and you’ll get your airplane in the air faster.”

Airlines aren’t willing to give up one of their biggest branding weapons just yet.

One of the latest carriers to unveil plush seating, Saudi startup Riyadh Air, ruled out any retreat from customisation.

“I want a brand that’s unique and that uniqueness is presented in the cabin,” CEO Tony Douglas told Reuters.

Additional reporting by Allison Lampert in Montreal, Joanna Plucinska in London, Rajesh Kumar Singh in Chicago and Lisa Barrington in Seoul; Editing by David Clarke
Stocks gain after weak ADP, gilt yields surge on finance minister worries

Market expectations for a July rate cut by the U.S. Federal Reserve climbed to just over 27%

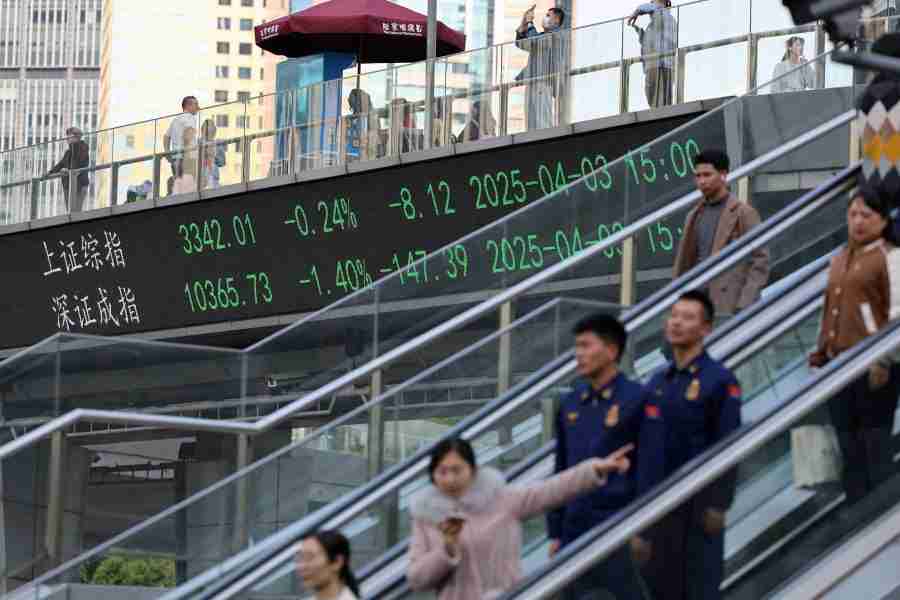
FILE PHOTO: FILE PHOTO: An electronic board shows Shanghai and Shenzhen stock indices as people walk on a pedestrian bridge at the Lujiazui financial district in Shanghai, China April 3, 2025. REUTERS/Go Nakamura/File Photo/File Photo

International News via Reuters:

Global stocks were roughly unchanged after U.S. data showed a surprisingly weak reading on the labor market while British government bond yields surged on growing speculation about the future of the country’s finance minister.

The ADP National Employment Report showed private payrolls dropped by 33,000 jobs last month after a downwardly revised 29,000 increase in May and well below the 95,000 increase expected by economists polled by Reuters.

The data comes ahead of Thursday’s government payrolls report, although there is little, if any, correlation between the two.

Market expectations for a July rate cut by the U.S. Federal Reserve climbed to just over 27% after the data, up from 20.7% in the prior session, according to CME’s FedWatch Tool.

“I take it as a mixed bag. On one hand, the wage is still strong, which is terribly important to the U.S. economy. On the downside, if this isn’t seasonality, this is the beginning of a long-term trend in white collar jobs that’ll spill over into the total labor market,” said Ross Mayfield, investment strategist at Baird in Louisville, Kentucky.

On Wall Street, the S&P 500 and Nasdaq were modestly higher, buoyed in part by a bounce in Tesla after the stock dropped 5.3% on Tuesday. Tesla shares were last up 4.5% after the electric automaker posted its quarterly deliveries.

The Dow Jones Industrial Average fell 41.48 points, or 0.09%, to 44,453.72, the S&P 500 rose 13.84 points, or 0.22%, to 6,211.70 and the Nasdaq Composite rose 138.79 points, or 0.69%, to 20,341.01. 

MSCI’s gauge of stocks across the globe rose 1.39 points, or 0.15%, to 918.79 and was on track for its fourth gain in the past five sessions, while the pan-European STOXX 600 index rose 0.09% as investors looked for signs of trade deals ahead of U.S. President Donald Trump’s July 9 tariff deadline.

Longer-dated U.S. Treasury yields rose, with the benchmark U.S. 10-year note up 4.8 basis points to 4.297%, while the shorter-end was lower after the ADP data.

The 2-year note yield, which typically moves in step with interest rate expectations for the Federal Reserve, fell 0.9 basis points to 3.768%.

British government bond yields surged, at one point jumping nearly 23 basis points, the most since October 2022, after finance minister Rachel Reeves appeared visibly distressed in parliament, a day after the government sharply scaled back plans to cut benefits.

The yield on the 10-year government bond, or gilt, was last up 11.5 basis points at 4.572%.

Sterling tumbled 1.17% to $1.3584 and was on pace for its biggest daily percentage drop since April 7.

The dollar index, which measures the greenback against a basket of currencies, rose 0.44% to 97.06 and was on track to snap a streak of nine straight declines, with the euro down 0.33% at $1.1766.

Trump said on social media on Wednesday that the U.S. has struck a trade deal with Vietnam. He had previously said he was not considering extending the deadline for countries to negotiate trade deals, even as negotiations with top trade partner Japan failed to make headway, although he expected a deal with India.

Investors were also watching for signs of progress in Trump’s massive tax and spending bill – which is expected to add $3.3 trillion to the national debt, slash taxes and reduce social safety net programs – as it now heads to the House of Representatives. Republican leaders set an initial procedural vote on the bill at 1300 GMT.

U.S. crude ticked up 0.03% to $65.47 a barrel and Brent rose to $67.23 per barrel, up 0.18% on the day as Iran suspended cooperation with the U.N. nuclear watchdog. But a surprise build in U.S. crude supplies limited gains.

Reporting by Chuck MikolajczakAdditional reporting by Sruthi Shankar and Nikhil Sharma in BengaluruEditing by Frances Kerry

BBC Radio News: Wednesday Noon – 2 July 2025

Dock workers divided over union stance, Branco secures City Council seat & AG warns against youth exposure to cannabis

Blockchain under the spotlight

Upcoming webinar will also focus on cybersecurity and regulatory compliance

Government press release:
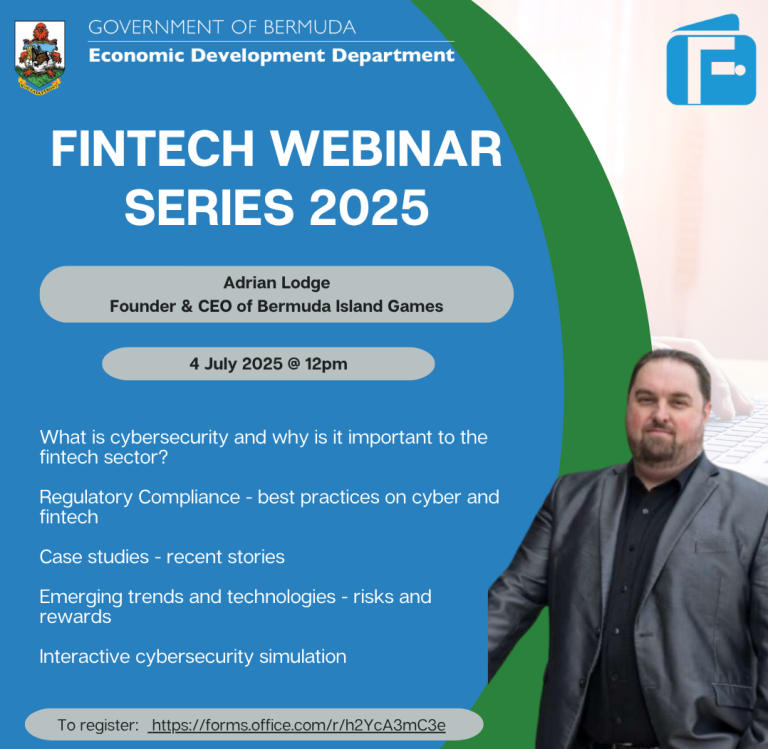
The Economic Development Department (EDD) is pleased to announce the next instalment in its Fintech Webinar Series 2025 on Friday, 4 July 2025, at 12:00 PM. This event will spotlight blockchain innovation through a live session featuring Adrian Lodge, Founder and CEO of Bermuda Island Games. Mr. Lodge is a Bermudian IT professional and entrepreneur focusing on web and mobile app development, e-commerce, and cybersecurity.
The virtual session is part of the Government’s ongoing efforts to promote education, engagement, and international collaboration in support of Bermuda’s Fintech ecosystem.
“I’m pleased to see the EDD’s FinTech Webinar Series continuing its vital work with a deep dive into cybersecurity,” said the Hon. Jason Hayward, JP MP, Minister of Economy & Labour. “The insights from our subject-matter experts on topics like regulatory compliance, emerging threats, and practical simulations will give participants a clear understanding of Bermuda’s robust framework for secure FinTech. This series firmly underscores our commitment to fostering secure innovation, supporting resilient economic growth, and positioning Bermuda as a premier jurisdiction for responsible and secure FinTech solutions.”
The presentation will offer participants an overview of Cybersecurity in Fintech, including:
– What is cybersecurity, and why is it important to the Intech sector
– Regulatory Compliance – best practices on cyber and fintech
– Recent case studies
– Emerging trends and technologies – risks and rewards, and
– Interactive cybersecurity simulation.
“I’m excited to share Bermuda’s commitment to a secure and compliant FinTech ecosystem,” said Adrian Lodge. “This webinar will offer clear insights into our cybersecurity regulations and best practices, showing how Bermuda is becoming a top choice for secure FinTech innovation. We’ll cover everything from core cybersecurity principles and recent case studies to emerging trends, all with an interactive simulation to help you effectively navigate today’s digital challenges.”
“We are excited to present this month’s webinar on Cybersecurity in Fintech,” said Ray Jones, Director of the EDD. “This session exemplifies our commitment to strengthening the security and compliance frameworks within our digital financial landscape, and positioning Bermuda as a jurisdiction of choice for innovative, ethical, and resilient FinTech solutions.”
This event aligns with Bermuda’s broader Economic Development Strategy, which seeks to leverage emerging technologies to generate new economic opportunities, develop skillsets, and attract strategic partnerships to the jurisdiction.
The webinar is open to the public, and those interested are encouraged to register early via the following link: https://forms.office.com/r/h2YcA3mC3e.

About the Economic Development Department (EDD):
The EDD is dedicated to advancing Bermuda’s economy through innovation, policy development, and industry support. By fostering an environment for digital transformation, the EDD plays a key role in ensuring Bermuda remains at the forefront of global economic trends. For more information, visit: www.gov.bm/department/economic-development-department. 

Exclusive: Dock workers divided over union stance

Some workers feel the vote for the overtime ban was intimidating

Dock workers are divided over union action being taken in response to the unfair dismissal of Chris Furbert Jr. in 2020.

Five long-serving Stevedoring Services employees approached Bermuda Broadcasting.

They say there are now about 14 out of 35 unionised port workers who were not employed at SSL at the time of the dismissal.

They feel that the voting process to implement the overtime ban was flawed and intimidating. Several members were not present at the union meeting, they say, and it was not a secret ballot – it was known who voted, and how.

We have confirmed that Chris Fubert Jr. was present at the meeting, but left ahead of the vote.

We understand between 21 and 23 members were present, and all but two voted in favour of the overtime ban.

The dock workers who spoke to us are concerned about the fact that this matter centres around the son of BIU President Chris Furbert.

They all agree that they would not be happy if the dismissed individual returned to work, and suggest this matter is creating a division between the newer port workers and those who have been there longer.

Some of the older staff, they say, are no longer attending union meetings.

Last year, a tribunal ruled that the dismissal of Chris Furbert Jr was unfair, because SSL had not followed its own grievance procedures.

The Tribunal awarded Mr Furbert Jr $250,000 in compensation, but did not order that he should be reinstated.

However, the union maintains that the Collective Bargaining Agreement requires that an unfairly dismissed employee must be reinstated and repaid all lost wages.

The BIU Port Workers Division implemented a six-month overtime ban, beginning in June, and the union stated that it could set a dangerous precedent for organised labour across Bermuda, if “employers can pick and choose which CBS articles to follow”.

Meanwhile, the BIU claims SSL brought in non-unionised workers to perform overtime work normally handled by BIU members. The union cited concerns about a return to a divisive practice in the 1940s, when “non-union “volunteers” were brought in to break the back of dockworkers’ collective action”.

However, Stevedoring boss Randy Rochester said the employees that the union may be referring to are long-serving SSL employees who choose not to be a part of the union.

“They are free to work when they wish”, Mr Rochester said.

Furthermore, the five port workers who spoke to Bermuda Broadcasting suggested the union’s comments are misleading, because the non-unionised workers who worked overtime on the weekend were responding to the emergency of a crane breaking down – it was not a normal case of overtime.

The industrial action continues.

US open to ‘creative solutions’ on pharma trade with EU, Irish minister says

The EU also wants a deal to cover commercial aircraft and parts, pharmaceuticals and semiconductors

International News via Reuters:

U.S. Trade Representative Jamieson Greer made clear in a meeting with Irish Trade Minster Simon Harris last month that Washington was open to “creative solutions” on pharmaceutical trade between the U.S. and European Union, Harris said on Wednesday.

“He made it clear that he was open to creative solutions when it comes to pharma and I think that’s an important recognition that actually pharma between the U.S. and the EU, the U.S. and Ireland, is much more interdependent than perhaps people were led to believe in certain quarters at the start of this process,” Harris told reporters.

The European Union wants immediate relief from tariffs in key sectors as part of any trade deal with the U.S. due by a July 9 deadline, EU diplomats have told Reuters, even as they accept the U.S. baseline tariff of 10% as unavoidable.

The EU also wants a deal to cover commercial aircraft and parts, pharmaceuticals and semiconductors, sectors the U.S. is investigating, but has not yet imposed extra duties on. Trump said in June the pharma duties would be announced “very soon”.

“I think it’s important to be truthful with people, the EU is negotiating with an administration that believes in tariffs and clearly I think 10% seems to be the baseline in any agreement they (the U.S.) have reached so far,” Harris said.

“But we will be seeking at an EU level to maximise the number of sectors where there is zero-for-zero (tariffs).”

Harris highlighted pharma, aviation and agriculture as areas Dublin would like trade between the EU and U.S. to flow freely.

He added that there was a welcome intensity to the talks between the EU and U.S. and that while a brief extension to the July 9 deadline is something that can considered, it would be preferable to at the very least deliver a framework agreement and set forward a roadmap for further engagement on key sectors.

Reporting by Conor Humphries, writing by Padraic Halpin; editing by William James and Chizu Nomiyama

Branco secures City council seat in by-election

Michael Branco triumphed over Mia Chambray by 32 votes

Michael Branco, new City of Hamilton councillor. Photo: Bermuda Parliamentary Registry

Finance and tech consultant Michael Branco was elected new City of Hamilton councillor last night in a by-election.

The Parliamentary Registry recorded 88 votes out of 387 registered business ratepayers. Mr. Branco secured the victory with 60 votes or 68.18%.

While first time candidate and city retailer, Mia Chambray earned 28 votes or 31.82% of the votes.

U-turns wipe out UK welfare savings and strain budget, analysts warn

The government backed down on its plan to make it harder to claim the Personal Independence Payment

International News via Reuters:

Prime Minister Keir Starmer’s U-turns to pass welfare reforms mean they will no longer save taxpayers any money and have shredded the margin Britain relies on to meet its fiscal rules, analysts said on Wednesday.

Starmer won a vote in parliament on his welfare plans on Tuesday, but only after his Labour Party lawmakers forced him to scale back cuts in a blow to the prime minister’s authority.

In particular, the government backed down on its plan to make it harder to claim the Personal Independence Payment, a benefit for people with health conditions.

Starmer had hoped his welfare reforms would save 5.5 billion pounds ($7.5 billion) in the current parliamentary term, which should end in 2029.

“Without reform to Personal Independence Payment, the watered-down bill is not expected to deliver any savings over the next four years,” said Helen Miller, the incoming director of the Institute for Fiscal Studies think-tank.

The reforms would create “huge” disparities between the treatment of existing and future claimants with health conditions and disabilities, the IFS added.

Tuesday’s vote, which saw 49 Labour lawmakers vote against the government, was bruising for Starmer, illustrating the breakdown in ties between his leadership team and parliamentarians and undermining his government’s goal of fiscal probity.

In a last-minute concession before the vote, the government said it would not finalise changes in eligibility for PIP until a review into the welfare system was completed – a move that a senior Labour lawmaker said could be reversed by reintroducing that section of the bill at a later date.

For now, Labour lawmakers are keen to suggest that unity has returned in the party in its pursuit of reforms, which Liz Kendall, work and pensions minister, admitted were “never easy, perhaps especially for Labour governments”.

The centre-left party has traditionally seen itself as the defender of Britain’s welfare state, built after World War Two.

Lawmakers will continue to scrutinise the bill on July 9.

BUDGET PLANS STRAINED

The watering down of the government’s welfare bill further strains finance minister Rachel Reeves’ budget plans, which hinge on a tiny buffer against the government’s self-imposed fiscal rules – equivalent to less than 1% of annual spending.

Reeves must also fund a partial reversal of cuts to winter fuel payments made to pensioners, as well as rising commitments to defence spending.

On Tuesday, the Office for Budget Responsibility said its past economic growth forecasts had been too optimistic, meaning it is likely to downgrade its projections for this year’s budget – another headache for Reeves.

“The welfare concessions last night blow a hole in Rachel Reeves’ fiscal rules. Combined with U-turns on fuel payments, her 9.9 billion pounds ($13.6 billion) of headroom has almost gone,” said Rob Wood, chief UK economist at consultancy Pantheon Macroeconomics.

“With the OBR signalling that it’s likely to downgrade long-term growth forecasts in the autumn, Reeves will have to raise taxes markedly again.”

While Britain’s government has borrowed slightly less than the OBR predicted during the first two months of the 2025/26 financial year, economists say budget plans could yet be knocked off course by a fractious global economy and conflicts abroad.

The British government bond market has become increasingly volatile in recent years, reflecting unease among investors over Britain’s mix of slow economic growth, high debt interest costs and persistent inflation.

($1 = 0.7297 pounds)

Reporting by Andy Bruce; additional reporting by Elizabeth Piper; Editing by Alex Richardson

BoE’s Taylor warns soft landing for UK economy at risk, sees more rate cuts

Charts published in Taylor’s speech showed interest rates could fall to around 2.25%

International News via Reuters:

Bank of England policymaker Alan Taylor said on Wednesday that a soft landing for Britain’s economy is now at risk and that economic data had recently argued for five interest rate cuts in 2025 rather than four.

“Previously, I had seen a UK soft landing in the cards, with some remaining upside risks to inflation from the bump in 2025,” Taylor said in a speech at a European Central Bank summit in Sintra, Portugal.

“Now I see that soft landing as being at risk, and greater probability of a downside scenario in 2026 pushing us off track, as demand weakness and trade disruptions build.”

Economists use the term “soft landing” for a situation where employment rises and economic growth continues after a cycle of rising interest rates.

Taylor has voted to cut interest rates in five out of seven Monetary Policy Committee meetings since he joined in September. In May, he backed an outsized 0.5 percentage-point cut, followed by a 0.25 percentage-point cut in June.

He told Bloomberg TV on Wednesday that he did not believe bigger interest rate cuts were necessarily needed.

However, having only eight Monetary Policy Committee meetings per year posed an “integer problem” for policymakers seeking a faster pace of easing, he told Bloomberg TV.

Taylor, who has caught the eye of economists since joining the MPC because of his clarity about his own expectations for the path of interest rates, said in his speech the MPC would be “well-served” by finding a vehicle for communicating its beliefs on future rates.

“After some shocks and noise clouded my view of the economy and global developments in the first quarter, my reading of the deteriorating outlook suggested to me that we needed to be on a lower rate path, needing five cuts in 2025 rather than the market-implied quarterly pace of four,” Taylor said.

Charts published in Taylor’s speech showed interest rates could fall to around 2.25% in the second half of next year if his downside scenario for the economy comes to fruition.

The BoE held interest rates at 4.25% last month, and investors are betting on the central bank to reduce borrowing costs in two further quarter-point moves to 3.75% by the end of the year.

Reporting by Suban Abdulla and Muvija M; Writing by Andy Bruce; Editing by William James and Alison Williams

ECB should keep rates at 2% unless new shocks hit, IMF says

The IMF is taking a different view than markets because it anticipates higher inflation next year than the ECB

International News via Reuters:

The European Central Bank should keep its deposit rate at the current 2% level unless new shocks materially change the inflation outlook, Alfred Kammer, head of the IMF’s European Department, said on Wednesday.

The ECB has cut rates by two percentage points since June 2024 but signalled a pause for this month, even if financial investors still see another cut to 1.75% later this year.

“Risks around euro zone inflation are two-sided,” Kammer told Reuters on the sidelines of the ECB Forum on Central Banking in Sintra, Portugal.

“This is why we think the ECB should stay the course and not move away from a 2% deposit rate unless there is a shock that materially changes the inflation outlook. Right now we don’t see anything of such magnitude.”

Part of the reason why the IMF is taking a different view than markets is because it anticipates higher inflation next year than the ECB.

The ECB projects price growth falling below its 2% target for 18 months from the third quarter, bottoming out at 1.4% in early 2026.

“For next year, we see inflation at 1.9%, which is above the ECB’s own projections, partly because we take a different view on energy prices,” Kammer said.

While most ECB policymakers see inflation risks balanced, there is an increasing group, including Finland’s Olli Rehn, Belgium’s Pierre Wunsch and Portugal’s Mario Centeno, who have all warned about the risk of inflation falling too low.

Reporting by Balazs Koranyi; editing by Mark Heinrich

Heatwaves may cut GDP by 0.5 pct points in Europe, Allianz says

Climate change is increasing the frequency and intensity of heatwaves, droughts and wildfires, with far-reaching economic repercussions

International News via Reuters:

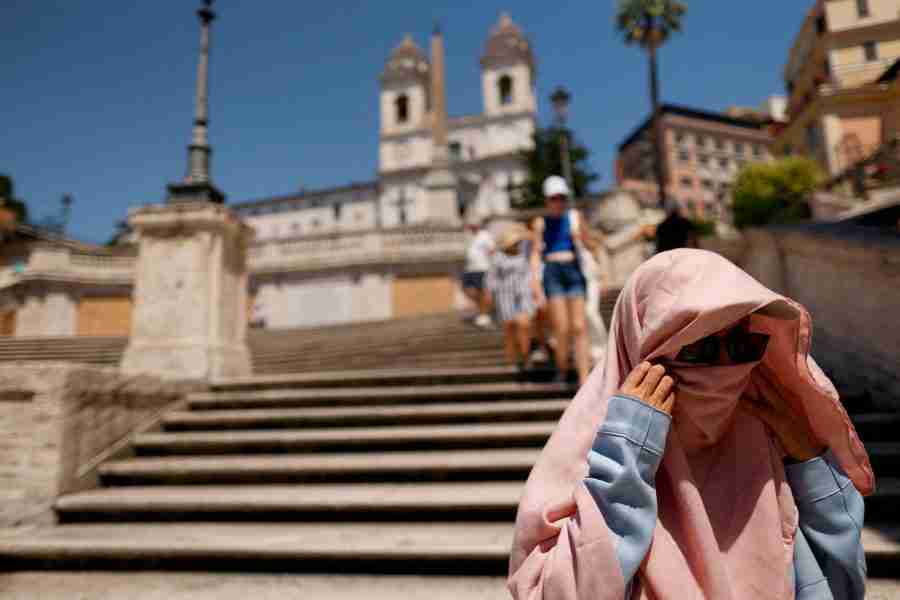
Recent heatwaves across Europe could slow economic growth in Europe by half a percentage point in 2025, a report by Allianz Research showed, comparing a day with temperatures above 32 degrees Celsius to half a day of strikes.

In Europe, GDP losses range from 0.1 percentage points for Germany to as much as 1.4 percentage points for Spain, where temperatures are around ten degrees higher in summer.

Climate change is increasing the frequency and intensity of heatwaves, droughts and wildfires, with far-reaching economic repercussions.

Globally, the heatwaves translate to a GDP reduction of 0.6 percentage points this year, Allianz Research said.

China, Spain, Italy and Greece could each see GDP losses of nearly one percentage point due to the current heatwaves, the Allianz Research report said, while the U.S. may face a decline of around 0.6 percentage points and France of up to a third of a point.

Extreme temperatures also reduce labour productivity, with the International Labour Organization forecasting that heat stress will reduce total potential working hours worldwide by 2.2% by 2030.

Productivity losses due to heat can be mitigated, Allianz Research said, calling for structural measures to prepare cities and adapt workplaces.

Reporting by Maria MartinezEditing by Ludwig Burger

Oil prices rise as Iran suspends cooperation with UN nuclear watchdog

Planned supply increases by the Organization of the Petroleum Exporting Countries appear already priced in by investors

International News via Reuters:

Oil futures edged up on Wednesday as Iran suspended cooperation with the U.N. nuclear watchdog and markets weighed expectations of more supply from major producers next month while the U.S. dollar softened further.

Brent crude added 60 cents, or 0.9%, to $67.71 a barrel at 1017 GMT, while U.S. West Texas Intermediate crude rose 55 cents, or 0.8%, at $66 a barrel.

Brent has traded between a high of $69.05 a barrel and low of $66.34 since June 25, as concerns of supply disruptions in the Middle East producing region have ebbed following the ceasefire between Iran and Israel.

Iran put into effect a law on Wednesday that stipulates that any future inspection of its nuclear sites by the International Atomic Energy Agency needs approval by Tehran’s Supreme National Security Council. The country has accused the institution of siding with Western countries and providing a justification for Israel’s air strikes.

“The market is pricing in some geopolitical risk premium from Iran’s move on the IAEA,” said Giovanni Staunovo, commodity analyst at UBS. “But this is about sentiment, there are no disruptions to oil.”

Planned supply increases by the Organization of the Petroleum Exporting Countries and its allies including Russia, know as OPEC+, appear already priced in by investors and are unlikely to catch markets off-guard again imminently, said Phillip Nova senior market analyst Priyanka Sachdeva.

Four OPEC+ sources told Reuters last week the group plans to raise output by 411,000 barrels per day next month when it meets on July 6, a similar amount to hikes agreed for May, June and July.

“We are all talking about additional supply coming to the market, but the supply has not really hit the market,” Staunovo said. “Probably because it’s being consumed domestically.”

Saudi Arabia lifted shipments in June by 450,000 bpd from May, according to data from Kpler, its highest in more than a year. However, overall OPEC+ exports are relatively flat to slightly down since March, Staunovo said. He expects this to persist over the summer as hot weather drives higher energy demand.

The greenback continued to weaken, falling to a 3-1/2-year low against major peers earlier on Wednesday. A weaker dollar tends to support oil prices, as it could boost demand for buyers paying in other currencies.

U.S. non-farm payrolls data due on Thursday will shape expectations around the depth and timing of interest rate cuts by the Federal Reserve in the second half of this year, said Tony Sycamore, analyst at IG.

Lower interest rates could spur economic activity which would in turn boost oil demand.

Official U.S. oil stockpile data from the Energy Information Administration is due Wednesday at 10:30 a.m. ET. [EIA/S]

American Petroleum Institute data late on Tuesday showed U.S. crude oil inventories rose by 680,000 barrels in the past week at a time when stockpiles typically draw amid the summer demand season, sources said.

Reporting by Anna Hirtenstein in London; Additional reporting by Sudarshan Varadhan and Trixie Yap in Singapore; Editing by Christian Schmollinger, Rachna Uppal and David Evans